
It might start small. A pipe leak. A storm pushing water under the door overnight. Maybe it’s a slow leak beneath the slab that only shows up months later as a warped floor. No matter how it began, you’re now faced with a house that needs work, and you’re unsure what those repairs might cost.
Water damage is hardly ever caught as early as people think it should have been. That’s not a sign you let something go. Water hides, and it moves.
Here in Southern California, water damage happens for reasons beyond just upkeep. Winter storms can arrive suddenly, dumping heavy rain in a short time. Many homes here are decades old, with aging plumbing quietly tucked inside walls. Plus, concrete slab foundations can hide leaks under the floor until the damage becomes obvious.
We’re Seller’s Advantage, a family-owned company right here in Southern California and a licensed California brokerage. We buy homes directly, water damage and all. But we also understand that sometimes, drying out, repairing, and listing your home can put more money in your pocket. If that’s your situation, we’ll say so.

Start With Where the Water Came From
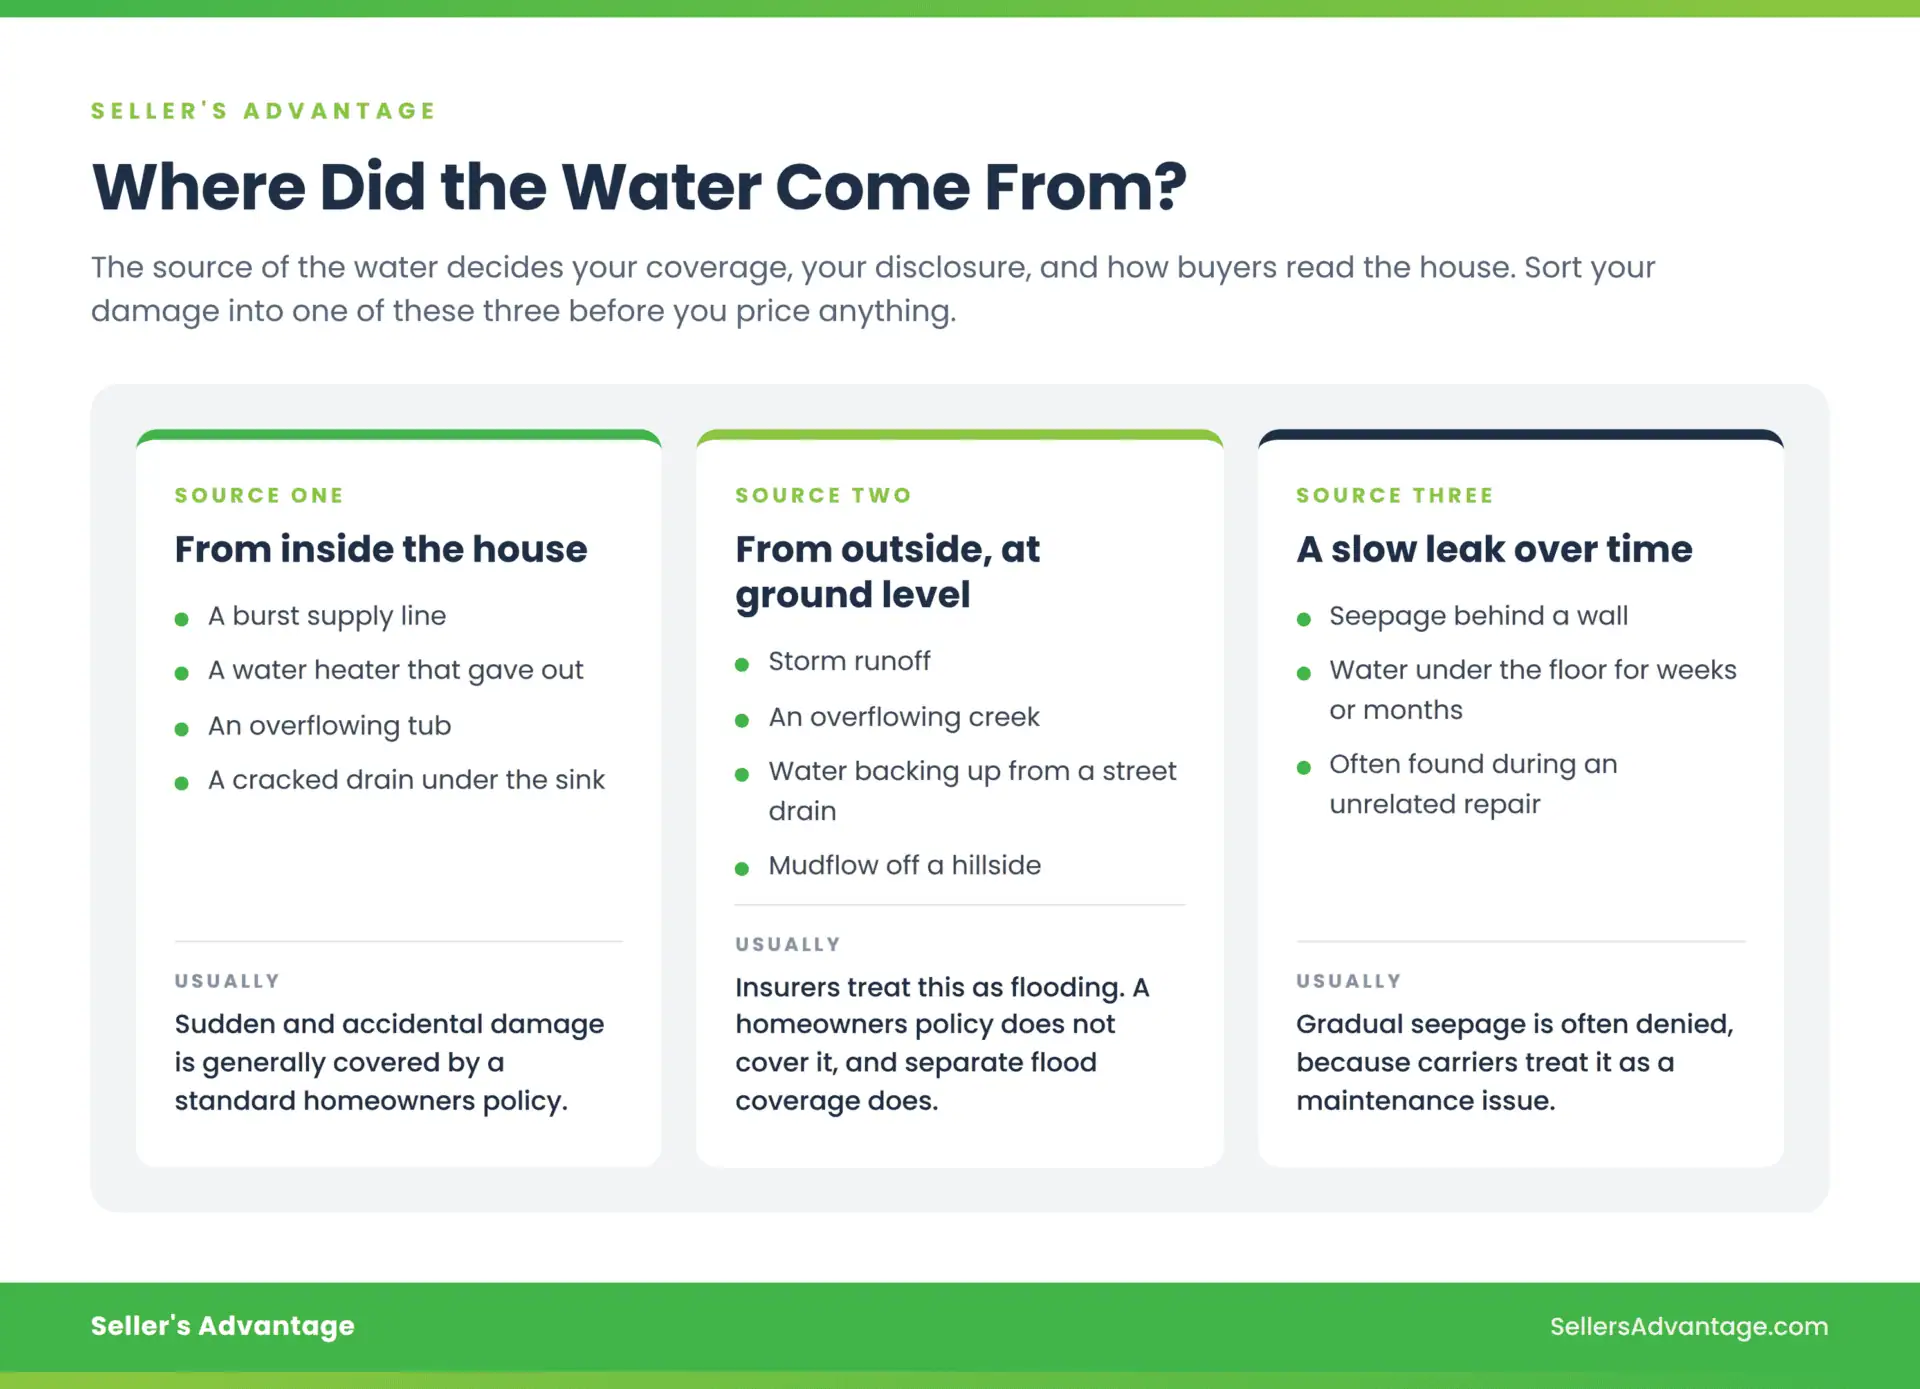
Before you price anything, you need to know one key thing: where did the water come from? That one fact shapes your insurance coverage, what you have to disclose, and how buyers will see your home.
Water damage that started inside the house is one thing. A burst pipe, a water heater that gave out, an overflowing tub, a cracked drain under the sink. The damage might be pretty bad, but at least the cause is contained and usually easier to explain.
Water from outside is a whole different story. Storm runoff, an overflowing creek, water backing up from a street drain, or mudflow rushing down a hillside, which is mud moving like a river across ground that is normally dry. Insurers treat all of it as flooding, no matter how the storm played out.
Then there’s the slow leak scenario, where water has been sneaking behind a wall or under the floor for weeks or even months. Often, homeowners only discover it during some unrelated repair.
Knowing which bucket you fall into is the first step, because it shapes your insurance answer and everything after it.
What Insurance Actually Pays For
This is the part that catches most owners off guard.
A standard California homeowners policy generally covers water damage that is sudden and accidental. The burst pipe qualifies. The failed water heater usually qualifies. Gradual seepage from a leak that ran for months usually does not, because carriers treat it as a maintenance issue rather than a sudden event.
Flooding sits outside the policy entirely. The California Department of Insurance clearly states that homeowners’ and commercial insurance policies typically exclude coverage for flood, mudslide, debris flow, and similar disasters. Coverage for these types of losses comes from a separate flood insurance policy, most commonly provided through the National Flood Insurance Program, a federal program administered by FEMA.Coverage for those losses comes from a separate flood policy, most often through the National Flood Insurance Program, a federal program run by FEMA.
Two details about flood policies matter to sellers. Building coverage tops out at $250,000 and contents coverage at $100,000 for a home. And a new policy takes 30 days to take effect, with a few narrow exceptions, so buying one after the storm does not help with the damage already done.
If you filed a claim, you have timing rights. Under California’s claim handling rules, your insurer must accept or deny the claim within 40 calendar days of receiving proof of claim. Once a claim is accepted, payment generally follows within 30 days.
Knowing what your policy will and will not fund tells you how much of the repair is yours to carry, which leads straight into what you owe a buyer in writing.
What You Have to Tell a Buyer
Some sellers worry that disclosing water damage will scare everyone off. In practice, the disclosure is what protects you, and understanding how selling a house as-is in California really works can make the process feel a lot less risky.
Sellers of most homes here complete a Transfer Disclosure Statement, the state form where you write down what you know about the property’s condition. It asks directly about water damage, flooding, and drainage problems. California law is explicit that this form cannot be waived in an as-is sale, meaning a sale where the buyer accepts the property in its current condition with no repairs from you.
There is a second form. The Natural Hazard Disclosure Statement tells the buyer whether the property sits in a mapped hazard zone. One of those zones is a Special Flood Hazard Area, which is FEMA’s designation for land with high flood risk. Another is a dam inundation area.
Keep every piece of paper. Plumber invoices, the drying company’s report, photos before and after, permits, insurance claim records. A repair you cannot prove tends to get treated as a repair that never happened.
If your damage involved mold, that carries its own disclosure duties, and we cover mold separately. What matters here is that hidden damage has a way of surfacing, which brings up the repair question itself.
Repairs, Permits, and the 50 Percent Rule
Getting a repair number is where a lot of sellers stall out, and the delay is understandable. The estimate often lands higher than expected.
Water travels. It runs along framing, soaks into subfloor, wicks up drywall, and collects in cabinet bases. A stain on the ceiling is a symptom, not a boundary. Contractors often open a wall and find more than what showed.
There is also a rule that surprises people in flood zones. Say your home sits in a Special Flood Hazard Area. If the cost to repair it reaches 50 percent or more of the structure’s market value before the damage, local officials can declare it substantially damaged. Land value is not counted. Once that call is made, the home has to be brought into compliance with current floodplain rules, which can mean elevating the structure, or in some cases demolishing it.
That determination comes from your city or county floodplain manager, not from FEMA. If your repair estimate is climbing toward half of what the structure is worth, ask your local building department where you stand before you sign a repair contract.
Permits matter too. Structural, electrical, and plumbing repairs generally require them. Unpermitted work becomes a disclosure item later, and usually a price deduction.
Once you have a real repair number and a permit answer, you can compare your options honestly, much like you would when deciding how to handle selling a California house that needs work.
Three Ways Sellers Handle This
There is no single right choice. It depends on your repair number, your cash, your timeline, and how much project management you have in you right now.
Repair, then list. Done well, this usually produces the highest gross sale price. It also means fronting the money, scheduling contractors in a booked season, and waiting. A traditional sale typically runs 90 to 120 days on the market, plus another 30 to 60 days in escrow. Escrow is the outside company that holds the money and the paperwork until every condition of the sale has been met.
List as-is with an agent. You skip the repairs and price the home to reflect its condition. Your buyer pool narrows, though. Financed buyers depend on appraisals, meaning the lender’s own valuation of the home, and on lender condition standards. Active water damage can stall or sink that approval.
Sell directly to a buyer who takes it in current condition. A direct cash offer comes in below what a repaired home would fetch on the open market. The buyer is absorbing the repair cost, plus the risk that the damage is worse than it looks. It is also one version of selling a house without a Realtor, since you work directly with the buyer. The number that matters is not the headline price. It is what lands in your hands after repairs, months of carrying costs, commissions, and closing costs come out of a traditional sale.
Run all three as net numbers, not gross ones. If the repaired-and-listed path nets you meaningfully more, take it.

Selling to Us With the Damage Still There
If a direct sale is the path you want to look at, this is how our sell my house fast, as-is process works on our end.
We come out and see the house. Nobody expects you to dry anything, tear anything out, or clean up a dirty or cluttered home first. After a member of our team has walked the property and seen the damage in person, you may get a no-obligation cash offer inside of 24 hours from a company that buys houses in any condition. We do not make offers off a web form. A number produced sight unseen is not a real number.
We don’t charge a commission. We cover government fees, transfer fees, recording fees, escrow fees, and title insurance, similar to our broader we buy houses in California program. You stay responsible for the mortgage payoff, any unpaid property taxes, and recorded liens, meaning claims filed against the property such as a contractor’s lien or a tax lien. A traditional mortgage loan also brings contingencies, the conditions a buyer can back out on if financing falls apart. A sale to us does not carry those.
Closing can come as early as 7 to 14 days, following the same basic steps as our broader guide on how to sell your property fast for cash. The date is yours, though. If you need longer to move, to finish a claim, or to wait on a family decision, we can stretch the timeline. We will not rush you out of your home.
Money moves in one direction at closing. The buyer wires funds into escrow, that company clears your loan payoff, recorded liens, and back property taxes out of them, and the balance is released to you. You never wire anything yourself.
Sellers who need money before the closing date can ask about an advance. On cash purchases, up to $20,000 can be released early against the proceeds you are already owed, then deducted at closing. Nothing is borrowed and nothing is added to your costs. It is there to help you start your next chapter while the paperwork finishes, whether the home is in Los Angeles or anywhere else we buy houses fast in Southern California.
An open claim does not have to stop a sale. Who keeps the claim payment is a term you negotiate, so raise it with your carrier early. We will walk you through that part.
Questions We Get About Water Damage
Do I have to repair the damage before I sell? No. California requires you to disclose what you know, not to fix it. Repairing raises what buyers will pay, and it is optional.
Will my insurance cover this? It depends on the source. Sudden and accidental water damage from inside the home is generally covered. Flooding is not covered by a homeowners policy at all, and a slow leak that ran for months is often denied as maintenance. Read your policy, and ask for any denial reason in writing.
Do I have to disclose damage that was repaired years ago? Yes, if you know about it. Past water intrusion is a material fact, and repaired damage is still damage that happened. Disclose it and attach the invoices.
Can I sell while my claim is still open? Often, yes. The sticking point is usually who receives the claim payment, which gets handled in the purchase contract. Tell your carrier what you are planning.
Is my house worth less because it flooded once? Some buyers discount it and some do not. How much depends on repair quality, documentation, and whether the property sits in a mapped flood zone. Good records narrow that gap more than anything else.
What if the city says my home is substantially damaged? That determination triggers current floodplain requirements, which can be expensive. Get the finding in writing, ask what compliance would require, and weigh that against every option.
Those are the ones we hear most. Yours may be different.
Talk It Through With Our Team
Standing in a damaged house, with an insurance answer you did not expect and a repair estimate you did not budget for, is hard. You do not have to sort it out by yourself, and you do not have to decide this week.
We will look at the house as it stands, give you a number with no obligation attached, and be straight about whether repairing and listing would serve you better. Sometimes it will. We would rather tell you that than buy a house you should have kept.
Talk with our local team about your water-damaged home →
Sources
- California Department of Insurance, Flood Insurance Resources
- FEMA National Flood Insurance Program, Buy a Flood Insurance Policy
- California Civil Code Section 1102.1
- FEMA, Understanding Substantial Damage Determinations
- California Code of Regulations, Title 10, Section 2695.7
Sell Your House Fast For Cash
We Buy Houses in Southern California As-Is
Close on your timeline and avoid the hassle of traditional fees.
Get My Free,
No-Obligation Quote
Call us today at 800-208-3243 and get an offer in as little as 24 hours. It’s quick and easy!
"*" indicates required fields
Southern California’s Most Trusted Home Buyers

