
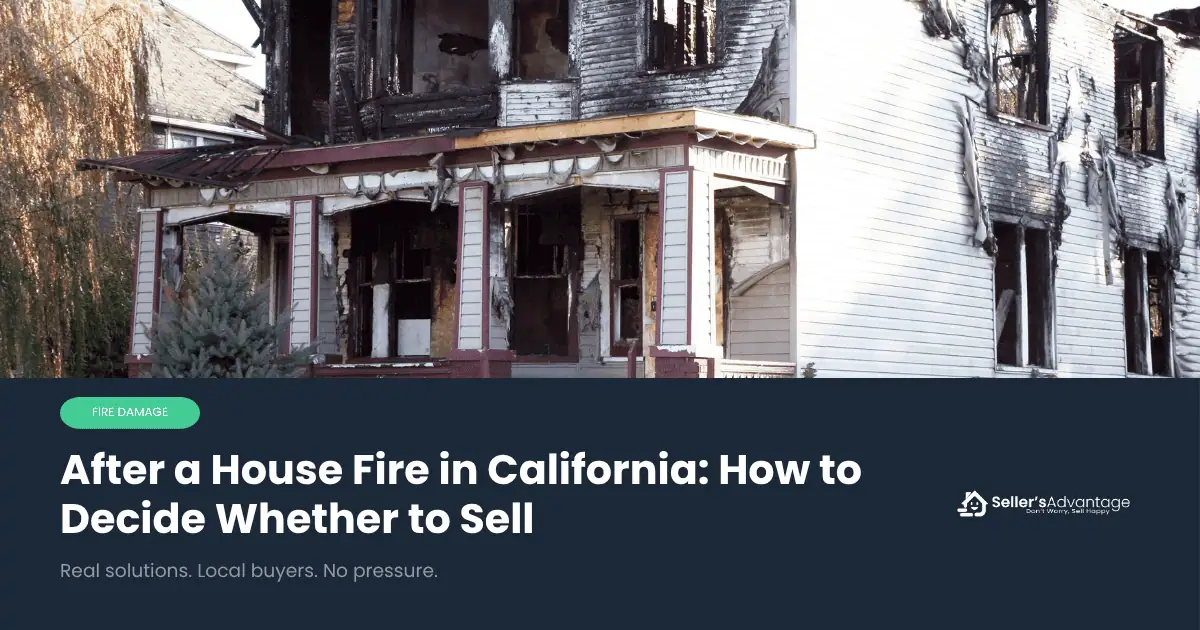
If you’re looking into how to sell a fire-damaged house in California, you’ve probably run into the same wall most homeowners hit. Nobody will give you a firm number on what the house is worth now, and the reason is that the sale price isn’t the number that matters most. That’s usually your insurance settlement, and it’s the one to get sorted out first.
We’re Seller’s Advantage, a family-owned, licensed Southern California brokerage, and we’ve spent years buying houses across the area. Being licensed means we’re regulated and accountable in ways an unlicensed operator isn’t, which matters more than usual right now, because homeowners in fire areas have been fielding a lot of unwanted attention lately. What follows is everything we’d want you to know before you decide whether to sell.
One note before we start. This is general education, not legal, tax, or insurance advice, and what applies to you depends on your policy, your loss date, and your county. Your own adjuster, a CPA, and a California real estate attorney are the people who can speak to your situation.
Why a Fire-Damaged House Won’t Sell Like Your Neighbor’s Did
It helps to start with how an ordinary California sale works, because that’s what fire damage interrupts.
A buyer applies for a mortgage. The lender orders an appraisal to confirm the house is worth what the buyer is paying, checks that the home meets its standards for a place someone can live in, and confirms the buyer has fire insurance lined up before it funds. Three quiet checks that an ordinary house clears without anyone thinking about them.
Fire damage stops all three at once. An appraiser has few or no comparable sales to work from, because half-burned houses don’t trade often enough to build a comparison. A lender won’t fund a home that can’t pass its habitability check, meaning its test for whether the place is livable. And a buyer can’t close without fire insurance, which is harder to come by on a property in a mapped fire hazard zone, meaning an area the state has classified by wildfire risk, carrying a recent claim.
So when you hear that financed offers on fire-damaged homes fall apart in escrow, that’s why. Nobody is acting in bad faith. Three systems all need the house to be in a condition it isn’t in yet.
Around here the effect compounds, because so much of Southern California’s housing sits inside high or very high fire hazard severity zones. An insurability question that would be a footnote in another state often turns out to be the deciding factor, and it’s a big part of why a local buyer will read your property differently than a national formula does.
Smoke and Water Damage Only? Different Situation
Now, not every fire loss results in a completely burned-down house. If your home isn’t fully destroyed, the situation is different.
Sometimes the structure itself remains intact, and the insurance company authorizes a cleaning. However, buyers may still leave after a brief inspection. This happens because smoke residue can settle deep into drywall, insulation, carpet padding, and the heating and air conditioning system, so the smell tends to come back when the weather turns. That’s a real problem and you’re not imagining it. Water used to fight the fire also works its way into subfloors and wall cavities that nobody looks at for months.
When the damage is partial, repairing and listing stays a realistic option, which often isn’t true after a total loss. Keep that door open as you read the rest of this.
Your Claim Matters More Than Your List Price
Whichever kind of loss you had, the same thing tends to drive the decision, and it isn’t the sale price.
If a cash number you’ve been quoted feels low, it’s often because it’s being measured against the wrong figure. A sale isn’t the only payment you receive after a fire. It’s one of two, and the claim is usually the larger one. What you decide to do with the property changes how much of that claim you end up collecting, and that’s the part almost nobody walks you through before you have to choose.
Your Payout Comes in Two Stages, Not One
Two terms do most of the work here, so they’re worth getting right.
Actual cash value is what it would cost to repair, rebuild, or replace what was lost, minus a fair deduction for age and wear on the parts of a house that normally get replaced over its life, like a roof or a water heater.
Replacement cost value is that same figure without the age deduction, capped at your policy limit. Which one your insurance payout reflects depends on your policy and on where you are in the process.
And that brings up the mechanic that catches almost everyone out. Where a policy requires you to actually repair, rebuild, or replace the property before it pays the full replacement cost, your insurer pays the lower figure first, then pays the difference once the property has been repaired, rebuilt, or replaced. So that gap between the two numbers isn’t automatically yours. It depends on what you do next, which is exactly why the sale decision and the claim decision belong together.
California does give you room to work it out, and more room than most people expect. For a loss tied to a declared state of emergency, you generally get at least 36 months from your first payment to collect the full replacement cost, with additional extensions sometimes available for good cause. Your insurer also generally can’t demand proof of loss, meaning the formal written statement of what you’re claiming, right away after the loss. Confirm the current rules and exact windows with your adjuster, since which version applies turns on the date of your loss.
Resource: California Department of Insurance, for current guidance on residential property insurance after a declared disaster.
You Can Take That Money and Buy Somewhere Else
There’s one more piece of your policy worth knowing about, and it’s the one we most often find homeowners haven’t been told.
After a total loss, California law places real limits on how an insurer can treat your building code upgrade coverage and your replacement cost coverage if you choose to buy an already built home somewhere else instead of rebuilding on your original lot. In plain terms, you are not required to rebuild on the same ground to collect what your policy is worth, though there are caps and conditions attached, and they depend on your specific policy.
What the rule gives you isn’t extra money. It’s a choice a lot of families never knew they had, and it’s why selling the lot and buying a finished home elsewhere can be a real strategy rather than giving up. Your adjuster and a real estate attorney can walk you through exactly how this applies to your policy.
Your Lender Is Holding the Check, and May Owe You Interest On It
Knowing what you’re owed is one thing. Getting your hands on it is often another, especially if there’s still a mortgage on the house.
Your lender is named on your policy, so payment is typically written to you and your lender together. You endorse it, the lender deposits it into what’s called a loss draft account, and the money comes back out in stages as an inspector confirms repair progress. Your mortgage lender, in other words, largely controls the timing while repairs are underway. The account belongs to them, which is why so many homeowners describe the money as existing but somehow out of reach, all while the regular bills keep arriving.
California has recently added protections around how these accounts are handled, including requirements around interest paid on funds held while your property is being rebuilt or repaired. The specifics are worth confirming directly with your servicer and, if anything looks off, a real estate attorney.
While you’re weighing your options, there are two things worth requesting in writing. The first is a mortgage payoff statement, sometimes called a payoff quote, which is the exact amount needed to close out your loan on a given date. Ask for it by that name, and keep in mind a quote is usually good for about 30 days, since interest accrues daily. The second is how your servicer would treat any funds still parked in the loss draft account if the property sells. That answer varies by loan and by claim status, and getting it early is one of the few pieces of this you can actually control.
If you do end up selling, the sale proceeds clear your loan the way they would in any sale, with closing costs coming out before anything reaches you.
The Property Tax Rule That Only Pays Off If You Sell
Money coming in is only half the picture. There’s also what you’d be giving up, and this is the part we’d most want a family member of ours to read.
Under Proposition 13, a California home is taxed on a value set when it was purchased or built, adjusted by no more than about 2 percent a year. That protected figure is your base year value, and on a long-held Southern California home it can sit far below what the house is actually worth. After a fire, you have to decide what happens to it. Three separate rules apply, and they genuinely don’t all point the same way. The exact thresholds and filing windows below are worth confirming with your county assessor before you rely on them, since they can vary by county and by disaster declaration.
While the home sits damaged, your county assessor may be able to reassess the property downward to reflect its damaged condition, which brings the tax bill down in the meantime, generally within a filing window that can be extended for specific declared disasters.
If you rebuild on the same site in a like or similar manner, your old base year value can come back, whatever the construction ends up costing, generally within a window that’s also extended for declared disasters. Here’s where we’ll argue against ourselves, because you should hear it from us rather than find it out later. That rebuilding relief belongs to whoever owned the property when it was damaged. Sell before the new construction is finished and the buyer doesn’t get it.
If you sell, Proposition 19 may let a homeowner whose primary residence was substantially damaged by wildfire or another proclaimed disaster move that base year value to a replacement primary residence anywhere in California, provided specific conditions around the extent of damage and the timing of the replacement purchase are met.
So the fork is a real one. Rebuild and keep the tax base on that lot, or sell damaged and carry the tax base to a new house. You don’t get both, and which one is worth more, and whether you even qualify, comes down to numbers and rules only your county assessor and a tax professional can confirm for your specific situation.
Resource: California State Board of Equalization, for the disaster relief guide covering damaged or destroyed property.
As-Is Doesn’t Mean You Stop Disclosing
If selling is looking like the likelier path, there’s one misunderstanding worth clearing up early, because it’s the one that tends to unwind deals in the final week.
Selling as-is means you aren’t making repairs. It doesn’t mean your disclosure obligations go away. California generally requires sellers to complete a Transfer Disclosure Statement, and known fire damage typically has to be disclosed on it, including damage that’s since been repaired, though the specific requirements can depend on the type of property and how the sale is structured. This is a question for a California real estate attorney before you sign anything, not something to assume from a summary like this one.
A few other disclosure-related requirements can come into play after a fire, and each one has specific conditions attached that are easy to get wrong from memory: a Natural Hazard Disclosure Statement covering whether the property sits in a mapped fire hazard zone, and, for some properties in higher-risk zones, documentation related to defensible space and, for older homes, fire hardening. The exact triggers, deadlines, and exceptions for these vary by situation, so rather than list specifics here that may not apply to your property, the right move is to ask your agent or attorney which of these actually apply to you and by when.
Worth gathering regardless: your claim paperwork, records of any cleanup or repair work done so far, and any permits pulled. It’s easier to hand a buyer a tidy folder than to answer the same questions five times.
Full disclosure works in your favor. A buyer who knew about the damage from the first conversation has nothing left to discover.
Resource: CAL FIRE, for defensible space requirements and inspection information.
Four Real Options, and Who Each One Fits
With the claim, the tax question, and your disclosure duties on the table, the choice itself starts to come into focus. There are four honest paths, and we’d rather lay all four out than steer you.
Rebuild and Stay
This fits when your claim covers most of the rebuild cost, when the lot itself is the point (the schools, the neighbors, the land), and when your household can absorb a long displacement. You keep the home and the neighborhood, and time is what you trade for it. In a burn scar area, rebuilding gets measured in years, because permitting, contractors, and materials are being competed for by everyone else who lost a house in the same fire. Two things do work in your favor while you wait: your base year value comes back, and additional living expense coverage for a loss tied to a declared emergency often runs well beyond a year, sometimes with extensions available where reconstruction delays are outside your control.
Repair, Then List With an Agent
This is usually the best fit for partial losses and smoke-only losses, where the repair is well defined and funded. It tends to produce the highest gross price.
Time is what you trade. The repair period moves at the speed of your loss draft releases and contractor availability, and only then does the listing start, commonly 90 to 120 days on the market plus another 30 to 60 days in escrow. Commission applies, and so do buyer inspection requests. Through all of it you’re carrying property taxes, insurance on a damaged or vacant home, utilities, and any mortgage.
List the Damaged Property As-Is With an Agent
This one works for sellers who have time and a lot that carries value on its own, especially after a total loss where what’s really being sold is the land. You reach the open market without doing any repairs, and in exchange the realistic buyer pool narrows to cash buyers and investors who take on repairs, so days on market run longer and any financed offer carries the fall-through risk we covered earlier.
Sell As-Is Directly to a Licensed Local Buyer
This fits when your household is out of state, when the claim is settled or close to it, when carrying costs are stacking up on an empty house, or when the rebuild math simply doesn’t work for your family. There are no repairs, no staging, and no showings, and we don’t charge a commission.
Once a member of our team walks the property, you can typically expect a no-obligation cash offer the same day or the next. Closing can land as early as 7 to 14 days from agreement, and if you’d rather have longer, the date goes where you want it. The offer comes in below what a fully repaired home would bring on the open market, because the buyer is taking on the repairs, the permits, and the risk.
What Actually Decides It Is Your Net
We’ll say plainly which of these beat us, because sometimes they do. Rebuilding usually wins when the claim is generous relative to rebuild cost, the household can wait, and the base year value on that lot is unusually low. Repair-and-list usually wins on a smoke-only loss where the fix is bounded and you aren’t paying for two places to live while it happens. And in a lot of Southern California neighborhoods, the lot carries much of the value all by itself, which changes the math again. None of those situations is rare. If yours is one of them, we’ll tell you so.
Between the two paths that end in a sale, what decides it is the net rather than the headline price. Many sellers find the final difference is smaller than they’d assumed once repairs, commission, months of carrying costs on a house nobody is living in, and the risk of a financed offer collapsing are all counted honestly. And your total recovery is the claim plus the sale, which is why the two decisions belong together.
Homeowners Have New Protections Against Unsolicited Offers
Before we describe how a sale with us works, there’s something worth knowing about how companies like ours are allowed to approach homeowners after a fire.
Following the January 2025 fires, homeowners in some Los Angeles and Ventura County areas reported a wave of unsolicited purchase offers, some well below what the property had been worth before the fire. California has since put restrictions in place limiting this kind of unsolicited outreach to fire-affected homeowners in certain areas, with real consequences for buyers who don’t comply.
If someone contacted you out of the blue about buying your fire-damaged property, that’s worth mentioning to a California real estate attorney, both to understand whether the outreach was compliant and, if you already signed something, whether you may have options to unwind it. The California Department of Real Estate is also a resource if you want to report unsolicited contact that felt off.
Seller’s Advantage only talks with homeowners who reach out to us first. That’s the whole policy.
Resource: California Department of Real Estate, for consumer alerts on unsolicited offers after wildfires.
How a Sale to Seller’s Advantage Works
If a direct sale turns out to fit your situation, this is what it actually looks like from your side.
The first call. You reach out and we talk through where things stand: whether the loss was total or partial, where your claim sits, whether your household is displaced, and what your timeline needs to look like. No pressure and no obligation.
Someone comes out to look. A member of our local team sees the property in person, or by video if that’s easier for you, usually inside a couple of days. You don’t need to clear anything out or fix anything beforehand.
An offer. After we’ve seen the home in person, you may have a no-obligation cash offer in hand within 24 hours. We build it around the property’s current state, the lot, and what the Southern California market is doing, and there are no contingencies, meaning conditions the sale has to satisfy before it can close, of the kind you’d find in a traditional mortgage loan.
Your closing date. The date is yours to choose. That date can be as early as 7 to 14 days, or we can push it out as far as you need. We won’t rush you out of your home, and if your claim is still open, the timeline can wait on it.
A cash advance, if the timing calls for it. On a cash purchase, up to $20,000 of your proceeds can be released before closing to help you start your next chapter. It comes out of what you’re already owed at closing, so there’s no loan and no fee attached.
Closing through escrow. Escrow means a neutral third party, a company with no stake on either side of the deal, holding the money and the paperwork until closing day. The buyer’s funds land there first. Your loan, any liens, meaning legal claims recorded against the property, and unpaid property taxes get cleared out of them, and the remainder is sent to you. Nothing gets wired by you at any point.
Our team holds your hand through the entire process and explains the paperwork in plain language.
One boundary worth stating outright, since this article covers so much insurance ground. We’re a licensed brokerage and a direct buyer, not an insurance company, an adjuster, or a public adjuster. We don’t handle claims and we don’t take an interest in yours. Those conversations belong with your own insurance professionals.
Questions We Get After a Fire
Do I keep the insurance money if I sell the house?
Payments already made to you are generally yours. What needs sorting out first is any money sitting in your lender’s loss draft account and the payoff owed at closing, both of which depend on your loan and where the claim stands. Ask your adjuster and your servicer in writing before you sign anything, and keep copies of what they send back.
Can I sell before my claim is settled?
Often, yes. It also changes what the claim ultimately pays, since the difference between the two payout figures can hinge on whether the property gets repaired, rebuilt, or replaced. Work through both decisions at the same time rather than one and then the other.
What if the house has been red-tagged?
A red tag is a notice from your local building department that the structure isn’t safe to occupy. It doesn’t stop a sale, though it does narrow the buyer pool to people paying cash, for the financing reasons above.
Will I owe taxes on the insurance payout?
Sometimes. Where a payout exceeds your tax basis in the property there can be a reportable gain, and there are rules that let that gain be postponed when the property is replaced. For a main home in a federally declared disaster area, the replacement period generally runs longer than usual. A tax professional can confirm the current rules for your situation.
Can I keep insurance on the house while I decide?
After a declared state of emergency, an insurer generally can’t cancel or refuse to renew a residential policy for a period of time for a property in or near the affected area, based solely on the fact that a wildfire happened there. If you’re displaced, additional living expenses coverage may help with temporary housing, so hold onto your receipts. Your agent or the Department of Insurance can confirm how any of it applies to your policy.
We inherited the house and then it burned. Where does that leave us?
Two processes layered on each other, each with its own timeline. Our guide to selling an inherited house in California covers the probate and authority side, and everything above still applies to the fire.
How fast can you close?
As early as 7 to 14 days, though the date is yours to set.
Helpful Resources
A few official sources worth bookmarking as you work through this, rather than relying on this guide alone for anything time-sensitive or specific to your situation.
- California Department of Insurance, for current notices and consumer guidance on residential property insurance after a declared disaster
- California State Board of Equalization, for the disaster relief guide on property tax reassessment for damaged or destroyed property
- California Department of Real Estate, for consumer alerts, including guidance on unsolicited offers after wildfires
- CAL FIRE, for defensible space requirements and inspection information
- IRS, for involuntary conversions and tax relief for disaster victims
- Consumer Financial Protection Bureau, for guidance on mortgage servicing and insurance loss draft accounts
- Your county assessor’s office, for property tax reassessment filings and current deadlines specific to your county
You Don’t Have to Rush This
If you’re considering selling your home after fire damage, we’re here to help you think it through.
There’s more time than it feels like. For a loss tied to a declared emergency, you generally have well over two years to collect your full replacement cost, and your county’s calamity relief has its own filing window. So get your claim answered and your numbers run before you decide anything.
When you’re ready to compare a direct sale against rebuilding or listing, we’ll go through all three with you. And if one of the others would leave you better off, we’ll say so.
Sell Your House Fast For Cash
We Buy Houses in Southern California As-Is
Close on your timeline and avoid the hassle of traditional fees.
Get My Free,
No-Obligation Quote
Call us today at 800-208-3243 and get an offer in as little as 24 hours. It’s quick and easy!
"*" indicates required fields
Southern California’s Most Trusted Home Buyers

