
The bills don’t arrive one at a time. They pile up, each with its own number and its own due date, and somewhere in that pile a thought creeps in. Maybe we have to sell the house.If that sounds familiar, you haven’t failed at anything. Illness drains savings fast, even for people who had insurance and money set aside.
We’re Seller’s Advantage, a family-owned brokerage licensed in California, and we buy homes directly across Southern California. For a lot of homeowners facing medical debt, selling isn’t the only answer, and it’s often not the first step.
Home prices here have climbed for decades, so plenty of families have built real equity even when the checking account looks empty. Equity is the difference between what your home is worth and what you still owe on it. It’s the money you can see, and it’s also the slowest to reach and the easiest to spend without quite meaning to. So before you reach for it, there are three free steps worth taking.
Step 1: Apply for the Hospital’s Financial Assistance
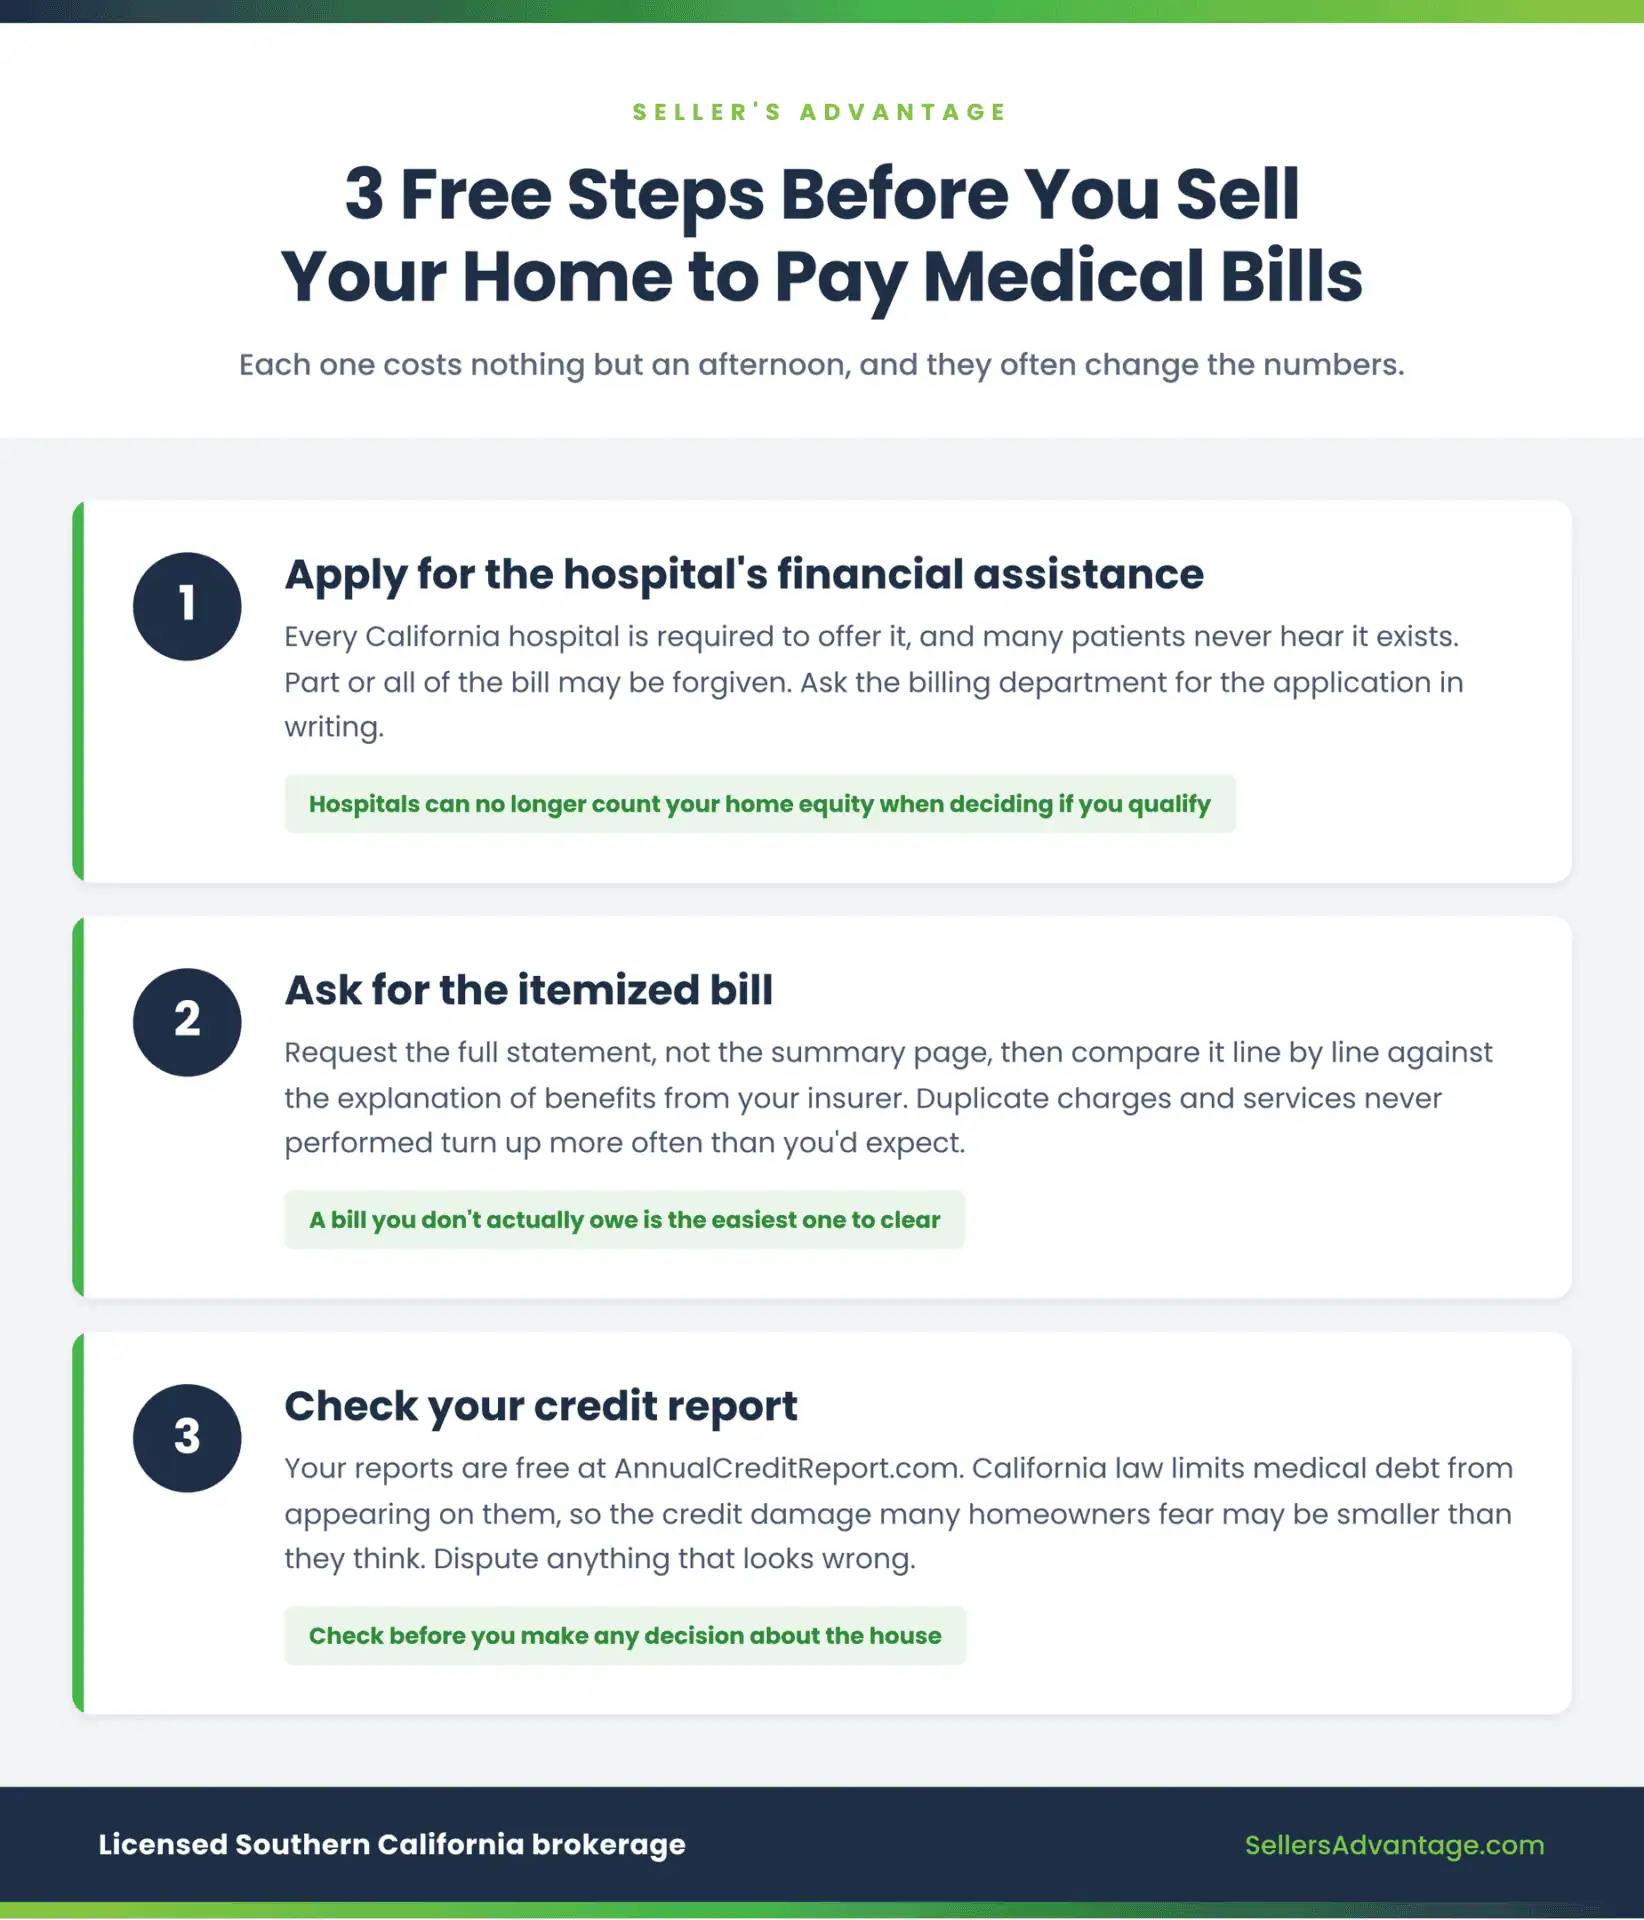
Every California hospital is required to offer financial assistance, but many people never hear about it. This assistance, often called charity care, means part or all of your medical bill could be forgiven. There’s also a discount policy that limits how much you’re expected to pay.
If your household income is at or below 400% of the federal poverty level, you can apply. That’s an income benchmark the federal government updates every year, and 400% of it reaches further up the income scale than most people expect.
An update took effect on January 1, 2025. Hospitals can no longer consider your assets, including your home equity, when deciding whether you qualify. Owning a home won’t disqualify you anymore.
To get started, ask the hospital’s billing department for the financial assistance application in writing. If you’re dismissed or ignored, you can file a complaint with the state through its Hospital Fair Billing Program.
We’ve seen homeowners come within days of selling, then cut their medical bills significantly through a program nobody had mentioned to them. While you wait to hear back, there’s one more thing worth checking.
Step 2: Ask for the Itemized Bill
Ask for the full itemized statement, not just the summary page. Then compare it against the explanation of benefits from your insurer, the document showing what was billed, what insurance covered, and what balance remains.
Go through it line by line. Duplicate charges and services that were never performed turn up more often than you’d expect. When something doesn’t add up, call the billing department and ask them to explain that specific item.
A bill you don’t actually owe is the easiest one to clear. Once you know the real number, the next worry is usually your credit.
Step 3: Check Your Credit Report
Your credit reports are free at AnnualCreditReport.com. Pull them before you decide anything about the house, because plenty of homeowners consider selling out of fear for their credit, and California law offers more protection than most people realize.
State law now prevents medical debt from being reported to credit agencies, and bars those agencies from listing it on your report. If someone reports it anyway, knowing better, the debt may become invalid and unenforceable. The Attorney General’s office explains it here.
This part can feel confusing, because the federal rules moved recently and you’ll find conflicting answers online. A federal rule that would have removed medical debt from credit reports nationwide was overturned in July 2025, and federal regulators now argue that state laws like California’s may not hold. No court has ruled on California’s law yet, and consumer advocates disagree with that reading.
So check the report yourself and dispute anything that doesn’t look right.
Those three steps deal with the bills themselves. The house is a separate question, and it’s usually where the real worry sits.
Why You Have More Time Than the Bills Make It Seem
California puts two protections between medical debt and your home.
The first involves liens. A lien is a legal claim on your property that has to be paid off before you can sell or refinance. Hospitals and emergency doctors already couldn’t place liens on your primary home if you qualify for financial assistance. Since January 1, 2025, that protection extends to collection agencies and debt buyers, closing a loophole that used to let them do what the hospital couldn’t.
Second, California generally protects your primary home from being sold off to satisfy a judgment on consumer debt, unless that debt was secured by your home when you took it on. Medical bills are ordinarily consumer debt. The rule sits in Code of Civil Procedure section 699.730, and it carries exceptions, so have a consumer attorney read your actual paperwork instead of relying on general guidance.
Owing a hospital doesn’t mean you’re about to lose your home. The distance between those two things is much longer here than the envelopes make it feel.
Sometimes, though, the three steps don’t close the gap.
When Selling Really Is the Right Move
Selling usually makes sense when the house itself has become the problem. If the mortgage, taxes, insurance, and upkeep are more than the household can carry going forward, selling protects the equity instead of watching it drain away a month at a time.
It also makes sense when your health changed what you need from a home. Stairs you can’t manage, a long drive to your care team, a yard nobody’s able to keep up with. Accessible homes are rarer than most people assume. Fewer than 4% of homes in the country have single-floor living, a no-step entry, and doorways wide enough for a wheelchair, according to the Harvard Joint Center for Housing Studies. Renovating is one answer. Moving is sometimes the shorter one.
And it makes sense when the gap is simply too big. Financial assistance and corrected billing can do a lot, but not everything, and at a certain scale the math is the math.
What we’d steer you away from is borrowing against the house to cover medical bills without thinking it through first. A home equity loan turns a debt with limited power over your home into one secured by it. That can be a fine trade with a good rate and steady income. It’s still a trade, and it deserves a real conversation with your bank and a financial professional. We’re a brokerage and a direct buyer, not a lender, and we can also walk you through selling California real estate after you’ve moved away.
If you do decide to sell, listing with a local agent often nets more when the home shows well and you can handle repairs and showings. A traditional listing usually runs 90 to 120 days on the market, plus another 30 to 60 days to close. Selling a house as-is in California, meaning you sell the home in its current condition without making repairs, trades some of that price for speed and certainty. Both are worth pricing out, and if listing clearly wins for you, we’ll tell you so.
Before you commit either way, two more things are worth a quick check.
Two Things People Miss Until It’s Too Late
If you’re on Medi-Cal or applying for it, talk to a Medi-Cal planner or a legal aid office before you sell anything. The home you live in gets treated differently from cash in the bank, and California reinstated an asset limit for certain Medi-Cal programs effective January 1, 2026, through AB 116 (Chapter 21, Statutes of 2025), the first phase of a return to 2022-era limits ($130,000 for an individual, plus $65,000 per additional household member). A second phase, full alignment with federal SSI resource limits, is a separate proposal not expected before 2027. (Department of Health Care Services / Justice in Aging)
The other is a tax question, and it works in your favor. If you itemize, unreimbursed medical and dental expenses above 7.5% of your adjusted gross income may be deductible (IRS Topic 502). Adjusted gross income is your total income minus certain deductions, and it’s the number near the bottom of your tax return. In a heavy medical year, that threshold is easier to clear than usual. Separately, if health is the main reason you’re moving and you haven’t owned the home long, the IRS allows a partial exclusion on the gain that most people assume they’ve lost. Tell your accountant about the medical situation specifically. We don’t give tax advice, but we can tell you which questions to bring.
If a direct sale does end up being the path, and you need to sell your property fast for cash, here’s what that looks like on our end.
How It Works With Us
It starts with a simple conversation. This is your time to share where you are at in life, the bills, your timeline, who’s still living in the home, what matters most to you. No pressure and no obligation. If another path serves you better, we’ll say so on that first call, even if that means choosing another fast cash home buyer in California, Las Vegas, or Phoenix.
Then someone from our local team walks the property, either in person or over video, generally within a day or two of that call. Don’t clean, don’t fix, don’t clear anything out. We buy homes in any condition, and nobody’s coming to judge how it looks. After we’ve seen the home in person, you may have a no-obligation cash offer in hand within 24 hours.
That offer will come in below what a fully repaired home might fetch on the open market, because we take on the repairs and the risk that comes with them. What matters is the number you actually walk away with once repairs, commissions, and months of carrying costs are accounted for. As a company that buys houses in California for fast cash, we don’t charge a commission, and we cover the standard closing costs, government fees, and transfer fees.
From there the calendar is yours. Closing can happen in as little as 7 days with a fast cash sale, or we can extend the timeline to fit your needs and pick a date that works around treatment, moving, or caregiving. We won’t rush you out of your home.
If money is tight while the sale comes together, ask about the cash advance. On cash purchases, we can release up to $20,000 of your proceeds early if the timing calls for it, to help you start your next chapter. It isn’t a loan and there’s no fee attached, just your own money arriving sooner.
Closing runs through escrow, a neutral company with no stake in either side of the deal. Escrow holds the money and the paperwork until closing. The buyer’s funds land there first, your mortgage and any liens get cleared, and the remainder is sent to you. If you’re wondering how to sell a house without a realtor and what that process looks like, nothing has to come out of your pocket to make that happen.
Our team stays with you through the whole process and explains every document clearly, so nothing at closing catches you off guard, and you can get to know the Seller’s Advantage team that supports your sale.
Questions We Get Most
Can a hospital take my house? For patients who qualify for a hospital’s financial assistance, hospitals, emergency physicians, and now collection agencies are barred from placing liens on a primary residence. California also generally protects a primary residence from forced sale over a consumer debt judgment, though exceptions exist. Have a consumer attorney look at your specific situation.
There’s already a lien on my house. Can I still sell? Usually, yes. Liens get handled through escrow and paid from the proceeds before the rest comes to you. Ask your lender early for a mortgage payoff statement, the document showing exactly what it takes to clear the loan. They’re typically good for about 30 days, since interest accrues daily.
Do I pay a commission or closing costs? We don’t charge a commission, and we cover the standard closing costs, government fees, and transfer fees. You’d still be responsible for your mortgage payoff, any recorded liens, and unpaid property taxes.
I’m in treatment and can’t handle showings. An as-is sale tends to make sense here. No showings, no open houses, nobody walking through while you’re recovering. A traditional listing asks for cleaning, scheduling, and repeat walkthroughs, which is a lot to carry during treatment. If you’re planning to sell your home as-is and want to understand the challenges, whether it’s the right financial call still depends on your numbers, and we’ll walk both paths with you.
You Don’t Have to Decide This Week
Three free steps, and none of them cost more than an afternoon. Apply for the hospital’s financial assistance, ask for the itemized bill, and check your credit report. People are often surprised by how much the numbers move.
If selling still looks like the right choice after that, we’ll talk it through with you honestly, including the times listing with an agent would put more in your pocket. Whatever life threw at you, you have more time and more room to move than the stack of envelopes suggests.
Talk with our local team about your situation →
Sell Your House Fast For Cash
We Buy Houses in Southern California As-Is
Close on your timeline and avoid the hassle of traditional fees.
Get My Free,
No-Obligation Quote
Call us today at 800-208-3243 and get an offer in as little as 24 hours. It’s quick and easy!
"*" indicates required fields
Southern California’s Most Trusted Home Buyers

